Insurance Basics That Actually Make Sense
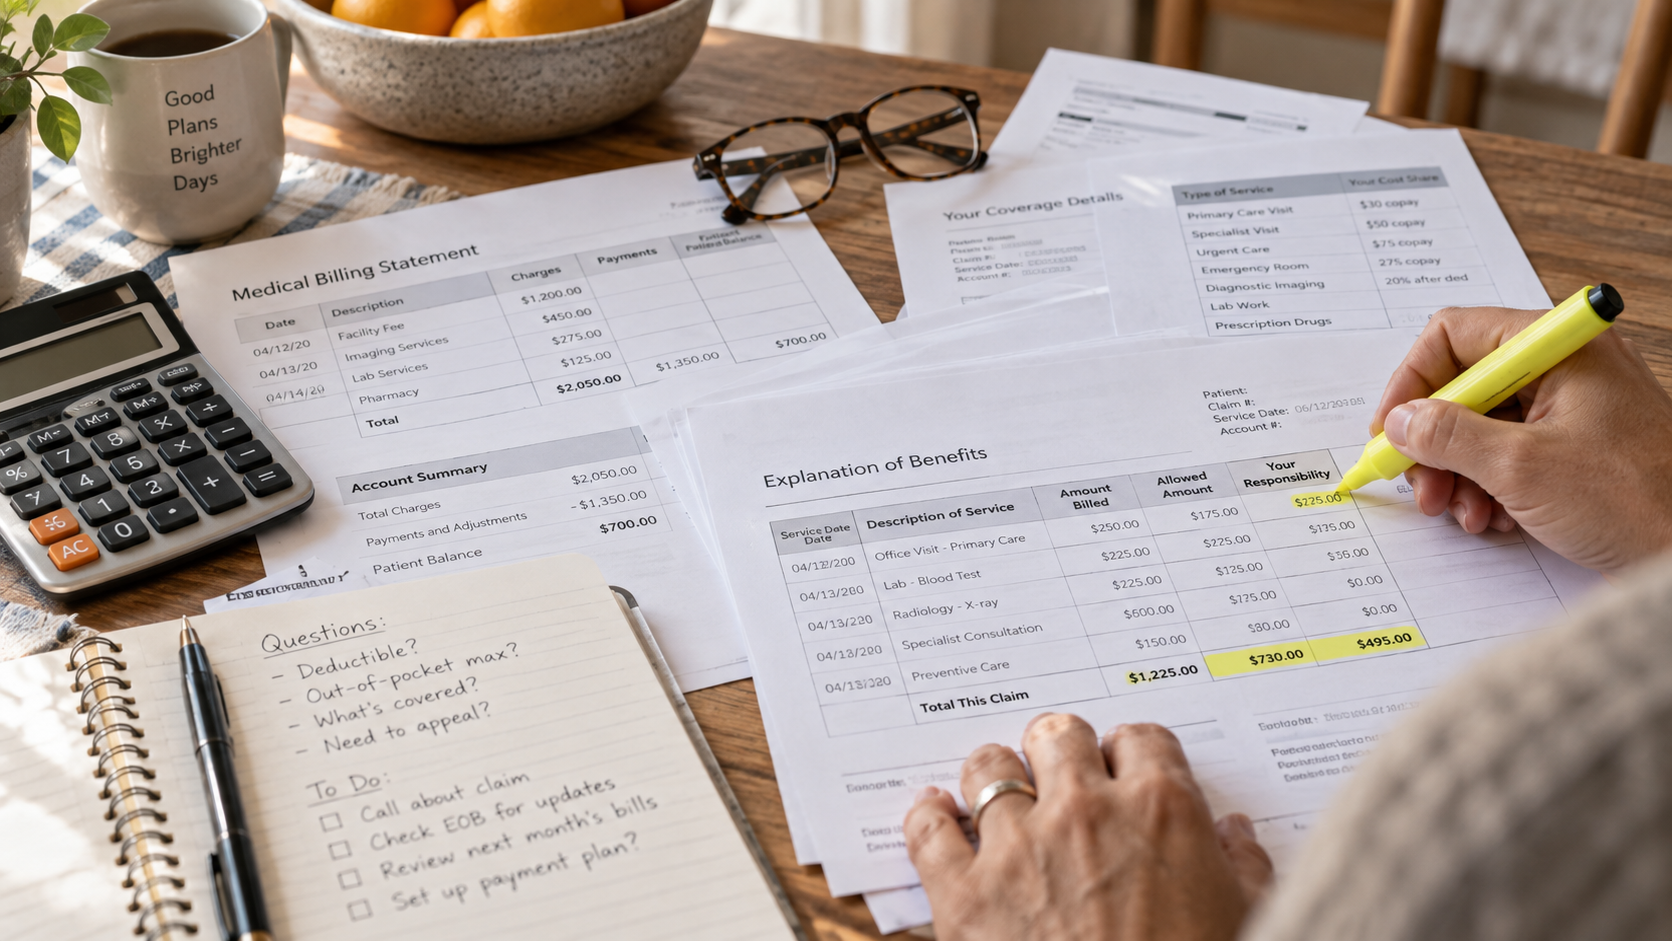
Always call your specific insurance company for their details.
There are more insurance policies out there than anyone can keep straight, and yours is probably structured differently than your neighbor's.
But having a basic understanding helps you ask better questions instead of feeling lost the moment someone starts throwing terms around.
Think of this as your cheat sheet.
The basic setup
Insurance: You pay money every month, and in return, they help cover your healthcare costs when you need care.
Premium: Your monthly cost to stay covered. You pay this whether you use healthcare that month or not.
Deductible: The amount you pay out of pocket before insurance starts helping. This usually resets every January 1st. Most preventive care, annual checkups, screenings, is typically covered fully even before you've met your deductible.
Coinsurance vs. copay, the two that get mixed up constantly
Coinsurance: A percentage you pay after your deductible is met. For example, 20% of the bill.
Copay: A flat dollar amount. For example, $30 for a doctor visit, regardless of what the visit actually costs.
A few things true of both: they usually don't count toward your deductible, since you've already met that. They do count toward your out-of-pocket maximum. And you keep paying them until you hit your yearly maximum.
This applies to doctor visits, specialist appointments, ER visits, urgent care, and prescriptions.
The safety net
Out-of-pocket costs: Any money that comes directly from your own pocket for medical care.
Maximum out-of-pocket: The most you'll pay in a year for covered services. Once you hit this number, insurance typically covers 100% for the rest of the year.
Worth knowing: this usually only applies to in-network care, and your monthly premiums don't count toward it.
The network question
In-network providers have a contract with your insurance and have agreed to certain rates, so your costs are lower.
Out-of-network providers don't have that contract. You'll pay significantly more, and sometimes insurance won't cover it at all.
Always confirm a provider is in-network before the appointment. "I thought they were covered" is one of the most common, and expensive, mistakes families make.
Health Savings Accounts (HSA)
If you have a high-deductible health plan, you may be eligible for an HSA.
You put pre-tax money into an account you can only use for healthcare expenses. Since it's pre-tax, you're effectively getting a discount on your medical costs. Some employers contribute to the account annually on top of that.
The catch: you have to have a high-deductible plan to qualify, and there are annual contribution limits.
Your checklist
Know your deductible amount
Know whether you have copays, coinsurance, or both
Know your out-of-pocket maximum
Keep a list of your in-network providers
Ask questions until it actually makes sense, not until you feel like you should stop asking
Insurance is complicated because there's a lot riding on the details. Don't feel bad about asking the same question three different ways until it lands.
Knowledge is what lets you advocate effectively and avoid the expensive surprises.