A Caregiver's Guide to Medicare Enrollment
If you're navigating Medicare, whether for yourself or for someone you love, you're already carrying enough. Insurance decisions on top of everything else can feel like one more thing you don't have room for.
Picking the right Medicare plan doesn't have to be complicated. It just takes understanding what's actually available and knowing which questions to ask.
Why this matters right now
Medicare Open Enrollment happens once a year. It's your window to look at your current coverage, compare what else is out there, and make a change if something isn't working.
For 2027 coverage, that window is
October 15 – December 7, 2026.
Miss it, and you're locked into your current plan for another year unless you qualify for a special circumstance. Paying attention now can save you real money and keep your healthcare where you need it to be.
Key Medicare enrollment dates (2026–2027)
Medicare Open Enrollment Period (Annual Election Period)
Dates: October 15 – December 7, 2026
Changes take effect: January 1, 2027
Who can use it: Anyone on Medicare
What you can do: Make any changes to your coverage, switch plans, drop coverage
Medicare Advantage Open Enrollment Period (for people already in Medicare Advantage)
Dates: January 1 – March 31, 2027
Changes take effect: The month after you enroll
Who can use it: People currently enrolled in a Medicare Advantage plan
What you can do: Switch to a different Medicare Advantage plan OR return to Original Medicare (only one change allowed)
5-Star Special Enrollment Period
Dates: December 8, 2026 – November 30, 2027
Who can use it: Anyone who lives in an area with a 5-star Medicare plan
What you can do: Switch to or stay with a highly-rated 5-star plan (one enrollment per window)
If your plan is terminating
Dates: December 8, 2026 – February 28, 2027
Who this applies to: People whose Medicare Advantage plan is ending
Action: Switch to a new plan. Aim for changes by December 31 to avoid a coverage gap.
The Medicare parts:
what you're actually choosing
Before you pick a plan, you need to know what's on the table. Medicare comes in parts, and your job is figuring out which combination fits your situation.
Medicare Part A (Hospital Insurance)
Covers inpatient hospital care, skilled nursing facility care, hospice, and some home health services. Most people don't pay a premium if they or their spouse paid Medicare taxes for 10+ years.
Medicare Part B (Medical Insurance)
Covers doctor visits, preventive services, outpatient care, and medical equipment. The standard premium for 2026 is $202.90 a month, though it can run higher depending on income. You'll also have copays and a deductible. CMS typically announces 2027 premiums in November, so those numbers aren't out yet as of this writing.
Original Medicare = Parts A + B combined. That's the federal option. It covers a lot, but not prescription drugs, dental, vision, or hearing.
Medicare Part D (Prescription Drug Coverage)
If you choose Original Medicare, you add Part D separately for drug coverage. It's picked alongside Parts A and B, not instead of them.
Medicare Part C (Medicare Advantage)
A private insurance alternative to Original Medicare. It bundles Parts A, B, and usually D into one plan, often with extras like dental, vision, and hearing. The trade-off is a network. You're generally limited to the doctors the plan covers, with some exceptions.
Original Medicare vs. Medicare Advantage: which is right for you?
This is the biggest call you'll make, and it comes down to your situation.
Choose Original Medicare + Part D if:
You want the flexibility to see any doctor, anywhere, no networks
You have specific doctors or hospitals you're not willing to give up
You want to add a Medigap plan to lower your out-of-pocket costs
You prefer the simplicity of federally-managed healthcare
Choose Medicare Advantage if:
You want everything bundled into one plan, no separate drug coverage to manage
You want extras like dental, vision, or hearing that Original Medicare skips
You're fine staying within a specific network
Your doctors and hospitals are already in that network
You want a lower or zero premium, and you're okay with higher copays in exchange
Important: If you're in Original Medicare and want to switch to Medicare Advantage, you can do that during Open Enrollment. If you're already in Medicare Advantage and want to go back to Original Medicare, think about a Medigap policy sooner rather than later. Wait too long, and you could face higher premiums or denials over pre-existing conditions.
The decision-making process, step by step
Step 1: Gather your information before December 7
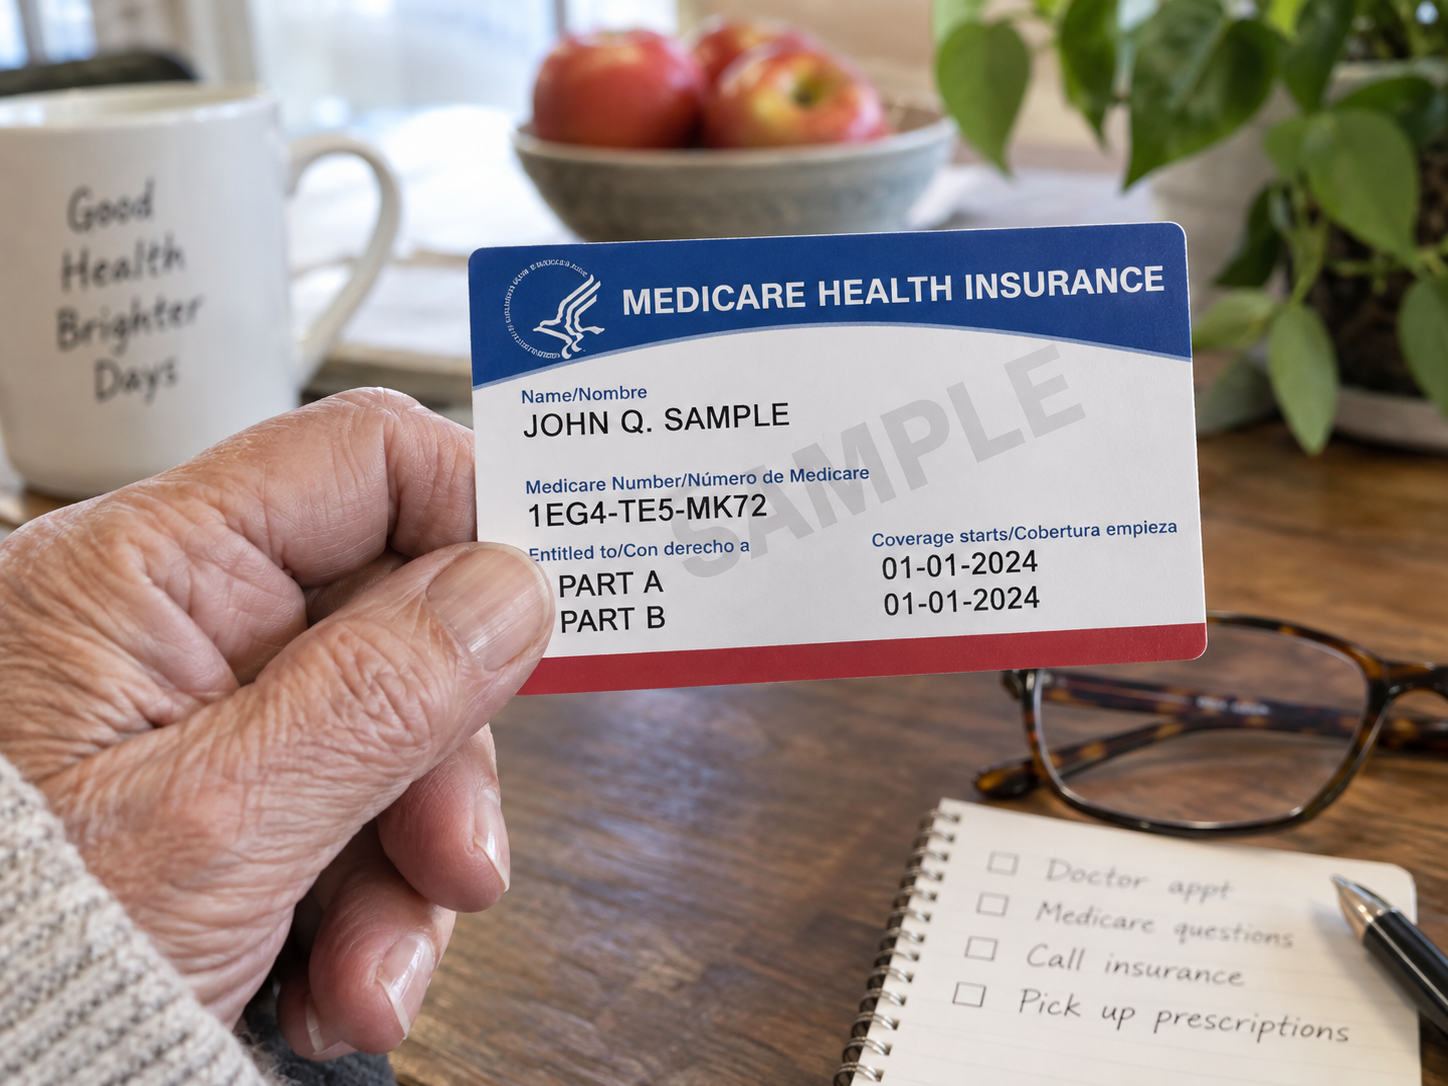
Your Medicare card, your Annual Notice of Change, your prescription list, and your current doctors and hospitals.
Step 2: Review what's changed
Plans shift every year. Premiums, copays, deductibles, covered drugs, in-network doctors, all of it. You'll get an Annual Notice of Change (ANOC) in the mail in September. Read it. It spells out exactly what's different for 2027.
Step 3: Use Medicare's Plan Finder
Go to Medicare.gov, enter your zip code, medications, and preferred doctors and pharmacies. It'll pull every available plan with costs and coverage side by side.
You can also call 1-800-MEDICARE (1-800-633-4227) and compare plans with a real person. It's free, and honestly, it helps when you're feeling lost in it.
Step 4: Compare costs across the whole year
Don't stop at the premium. Add it up: premium plus deductible plus copays for the drugs and visits you'll actually use. A $0 premium plan can still cost you $3,000 more in copays. Do the math before you decide.
Step 5: Verify network coverage
Considering Medicare Advantage? Call the plan directly and confirm your doctors and hospitals are in-network. Don't take the website's word for it. Networks change.
Step 6: Make your decision and enroll
Enroll through Medicare.gov, by calling 1-800-MEDICARE, or by calling the plan directly. Make sure it's in before December 7 for 2027 coverage.
Write it down. Date, time, who you talked to, what they told you. If something goes sideways later, you'll have the record.
For caregivers helping a loved one
If you're helping a parent or relative through this, your job is advocate, not decision-maker, unless they truly can't decide for themselves.
Bring them into it. Ask which doctors they want to keep. Ask what medications they're on. Ask if dental or vision coverage matters to them. Their answers should drive the choice, not yours.
If cognitive changes make this hard for them, you may need to take a firmer hand. But the goal stays the same: honor what they'd want, as much as you possibly can.
What happens after you enroll
Once your changes are in during Open Enrollment, your new coverage starts January 1, 2027.
New cards arrive by December 31. Hold onto the old ones until you know the new plan is working. Start using the new one on January 1.
If something's wrong, the plan doesn't fit, your doctor isn't really in-network, you're not happy, Medicare Advantage enrollees get another window from January 1 to March 31 to make one change.
Original Medicare enrollees don't get that same do-over. You're in it until next October.
The bottom line
Medicare is complicated, but broken into pieces, it's manageable. Your job is to understand the options, get real information, do the math, and pick what actually works for you.
You don't have to become an insurance expert. You just have to ask the right questions and not let the deadline slide past you.
Open Enrollment ends December 7, 2026. That's your window. Use it.
Need help?
Medicare.gov Plan Finder tool
Call 1-800-MEDICARE (1-800-633-4227) for free plan comparison help
Your local State Health Insurance Assistance Program (SHIP) for free, personalized guidance
Your doctor's office can often verify in-network status for plans you're weighing
This is complex work. It's also doable work. And getting it right matters.